Saving Money on Utilities: Tips and Tricks

**Saving Money on Utilities: Practical Tips for Every Household**

Utility bills can often feel like a never-ending drain on your finances, but with a few smart adjustments, you can significantly reduce your monthly expenses. The key is to adopt a combination of small, daily habits and long-term investments that pay off over time. Start by understanding your usage patterns—many utility providers offer detailed breakdowns of your consumption, which can help identify areas for improvement. For instance, are you using more electricity during peak hours? Simple changes like running appliances late at night or early in the morning can lower costs. Additionally, consider investing in energy-efficient appliances, as they consume less power and often come with rebates or tax incentives.

One of the most effective ways to save on utilities is to focus on heating and cooling, which typically account for a large portion of your bill. During colder months, seal gaps around windows and doors to prevent heat loss. Weatherstripping and draft stoppers are affordable and easy to install. In warmer weather, use ceiling fans and open windows strategically to circulate air instead of relying solely on air conditioning. Programmable thermostats are another game-changer—they allow you to set temperature schedules, ensuring your HVAC system isn’t working overtime when you’re away or asleep.

Water bills can also be trimmed with minimal effort. Start by fixing leaks, as even a small drip can waste hundreds of gallons annually. Install low-flow showerheads and faucets, which reduce water usage without sacrificing pressure. For laundry and dishes, wait until you have full loads before running machines, and opt for cold water cycles whenever possible. Outside, consider replacing thirsty lawns with drought-resistant plants or using rain barrels to collect water for gardening. These small changes add up quickly, both in savings and environmental impact.

Lighting is another area where you can cut costs without compromising comfort. Replace traditional incandescent bulbs with LED lights, which use up to 75% less energy and last much longer. Take advantage of natural light during the day by keeping curtains open, and remember to turn off lights when leaving a room. Motion sensors or timers can also ensure lights aren’t left on unnecessarily. If you’re feeling ambitious, consider installing solar-powered outdoor lighting, which eliminates electricity usage entirely for those fixtures.

Your kitchen is a hotspot for energy consumption, but there are plenty of ways to make it more efficient. Use microwave ovens or toaster ovens for small meals instead of heating up a full-size oven. Keep refrigerator and freezer doors closed as much as possible, and ensure they’re set to the right temperature—around 37°F for the fridge and 0°F for the freezer. Regularly clean coils on the back or bottom of your fridge to help it run more efficiently. Finally, avoid overloading your dishwasher and let dishes air-dry instead of using the heated dry cycle.

Laundry habits can also impact your utility bills. Wash clothes in cold water whenever possible, as heating water accounts for about 90% of the energy used by washing machines. Use high-spin settings to reduce drying time, and clean the lint filter after every load to improve dryer efficiency. If weather permits, air-dry clothes on a rack or clothesline. For those with gas dryers, ensure proper ventilation to avoid inefficiency and safety hazards.

Technology can be your ally in the quest to save on utilities. Smart home devices like smart plugs and energy monitors provide real-time data on your usage, helping you identify energy hogs. Apps from utility companies often offer tips tailored to your consumption patterns and even allow you to track your progress. Some providers also offer incentives for reducing usage during peak hours, so check if you qualify for such programs.

Don’t overlook the power of maintenance in keeping utility costs down. Regularly clean or replace air filters in your HVAC system to ensure it runs efficiently. Insulate your water heater and pipes to prevent heat loss, and consider installing a tankless water heater if you’re due for an upgrade. For older homes, investing in better insulation for walls, attics, and basements can yield significant long-term savings by reducing the workload on heating and cooling systems.

Community and government resources can also help you save. Many local utilities offer free energy audits to identify inefficiencies in your home. Rebate programs for energy-efficient upgrades are common, as are tax credits for renewable energy installations like solar panels. Nonprofit organizations and government agencies often provide grants or low-interest loans for home improvements aimed at reducing energy consumption.

Finally, consider adopting a mindset of mindful consumption. Simple actions like turning off the tap while brushing your teeth, unplugging devices when not in use, and opting for energy-saving modes on electronics can make a big difference. Encourage family members to join in—saving on utilities is a team effort that benefits everyone. Small changes today can lead to substantial savings tomorrow.

By combining these tips and tricks, you can take control of your utility bills and free up funds for other priorities. Whether you’re making minor adjustments or investing in major upgrades, every step counts. Start today, and watch your savings grow while reducing your environmental footprint.
How to Build an Emergency Fund on a Tight Budget

**Building an Emergency Fund on a Tight Budget: A Practical Guide**

Life is unpredictable, and having an emergency fund can provide a safety net during unexpected financial challenges. Whether it’s a medical expense, car repair, or job loss, having savings set aside can prevent debt and stress. However, building an emergency fund on a tight budget may seem daunting. With careful planning and small adjustments, it’s entirely achievable. Start by assessing your current financial situation. Track your income and expenses to identify areas where you can cut back. Even small savings, like reducing dining out or canceling unused subscriptions, can add up over time.

Once you’ve identified potential savings, set a realistic goal for your emergency fund. Financial experts recommend saving three to six months’ worth of living expenses, but even $500 can make a difference. Break your goal into smaller, manageable milestones to stay motivated. For example, aim to save $100 per month instead of focusing on the larger sum. Celebrate each milestone to keep yourself on track and maintain momentum.

Automating your savings is a powerful strategy. Set up a direct deposit or automatic transfer from your checking account to a dedicated savings account. This way, you save effortlessly without constantly thinking about it. Many banks allow you to schedule recurring transfers, making it easier to stick to your plan. Treat your emergency fund like a non-negotiable bill to ensure consistency.

Finding extra income can accelerate your savings. Consider taking on a side hustle, selling unused items, or freelancing in your spare time. Even temporary gigs, like pet sitting or tutoring, can provide additional cash. Allocate this extra income directly to your emergency fund to boost your progress. Every dollar counts, so don’t underestimate small earnings.

Reducing unnecessary expenses is another key to building your fund. Review your monthly bills and negotiate lower rates on services like cable, internet, or insurance. Switch to cheaper alternatives, such as generic brands or secondhand items, to save on everyday purchases. Cooking at home instead of eating out can also free up significant funds. These changes may require discipline, but they’ll pay off in the long run.

Stay accountable by tracking your progress regularly. Use budgeting apps or spreadsheets to monitor your savings and expenses. Visualizing your growth can keep you motivated and help you identify areas for improvement. Share your goal with a trusted friend or family member who can encourage you along the way.

Avoid dipping into your emergency fund for non-essential expenses. It’s tempting to use the savings for vacations or impulse buys, but this defeats the purpose. Remind yourself that the fund is for genuine emergencies only. If you do need to use it, replenish it as soon as possible to maintain your financial safety net.

Consider high-yield savings accounts to maximize your emergency fund’s growth. These accounts offer higher interest rates than traditional savings accounts, allowing your money to work harder for you. Shop around for accounts with no fees and easy access to your funds when needed.

Stay patient and persistent. Building an emergency fund on a tight budget takes time, but every step forward is progress. Focus on consistency rather than perfection. Even if you can only save a small amount each month, it’s better than nothing. Over time, these small contributions will add up to a significant cushion.

Prepare for setbacks by staying flexible. Life happens, and there may be months when you can’t save as much as planned. Don’t let this discourage you. Adjust your timeline if necessary and keep moving forward. The goal is to build a habit of saving, not to achieve perfection.

Educate yourself about personal finance to make informed decisions. Read books, listen to podcasts, or take online courses to learn strategies for budgeting, saving, and investing. The more you understand, the better equipped you’ll be to manage your finances effectively. Knowledge is a powerful tool in achieving financial security.

Finally, celebrate your success when you reach your emergency fund goal. Building savings on a tight budget is a significant accomplishment. Take pride in your hard work and use the momentum to set new financial goals. Whether it’s paying off debt, investing, or saving for a big purchase, your emergency fund is just the beginning of a brighter financial future.

By following these steps, you can build an emergency fund even on a tight budget. It requires discipline, creativity, and patience, but the peace of mind it provides is well worth the effort. Start today, and take control of your financial well-being.

How to Create a Monthly Budget That Works

**Creating a Monthly Budget That Works: A Step-by-Step Guide**

Managing your finances doesn’t have to feel like solving a puzzle. A well-structured monthly budget can give you control over your money, reduce stress, and help you achieve your financial goals. The key is to create a plan that’s realistic, flexible, and tailored to your lifestyle. Start by understanding your income and expenses, then build a system that works for you. Whether you’re saving for a vacation, paying off debt, or simply trying to spend less, a budget is your roadmap to financial success. It’s not about restricting yourself but about making intentional choices with your money. With the right approach, budgeting can become a habit that empowers you rather than overwhelms you.

The first step in creating a budget is to identify your total monthly income. This includes your salary, freelance earnings, side hustles, or any other sources of money. Be sure to use your *net income* (the amount after taxes and deductions) for accuracy. Once you know how much you’re bringing in, list all your monthly expenses. Divide them into two categories: fixed expenses (rent, utilities, insurance) and variable expenses (groceries, entertainment, dining out). Tracking your spending for a month can help you spot patterns and areas where you might be overspending. Many budgeting apps and spreadsheets can simplify this process, but a pen and paper work just as well if you prefer a hands-on approach.

Next, allocate your money using a budgeting method that suits your needs. The **50/30/20 rule** is a popular choice: 50% of your income goes to needs, 30% to wants, and 20% to savings and debt repayment. However, this isn’t a one-size-fits-all solution. If you’re paying off high-interest debt, you might need to adjust the percentages. Another option is the **zero-based budget**, where every dollar is assigned a purpose, ensuring no money is left unaccounted for. Experiment with different methods to find what works best for your financial situation and goals.

One common mistake people make is creating a budget that’s too restrictive. If you cut out all the fun, you’re less likely to stick with it. Allow yourself a reasonable amount for leisure activities, whether it’s dining out, hobbies, or shopping. The key is to prioritize what truly matters to you and cut back on unnecessary expenses. For example, instead of canceling your streaming subscriptions entirely, choose one or two that you use most often. Small, sustainable changes are more effective than drastic measures that leave you feeling deprived.

Life is unpredictable, and your budget should account for that. Build an emergency fund to cover unexpected expenses like car repairs or medical bills. Aim to save at least three to six months’ worth of living expenses, but even a small cushion can provide peace of mind. Additionally, plan for irregular expenses like holiday gifts or annual subscriptions by setting aside a little each month. This way, you won’t be caught off guard when these costs arise.

A budget isn’t a set-it-and-forget-it tool—it requires regular maintenance. Review your spending at least once a month to ensure you’re staying on track. If you notice you’re consistently overspending in one area, adjust your budget or find ways to cut costs. Celebrate your successes, no matter how small, to stay motivated. Remember, budgeting is a journey, and it’s okay to make adjustments as your financial situation evolves.

Technology can make budgeting easier and more efficient. Apps like Mint, YNAB (You Need a Budget), and EveryDollar sync with your bank accounts to track spending automatically. Spreadsheets are another great option if you prefer a DIY approach. Whichever tool you choose, the goal is to make budgeting as seamless as possible. Set reminders to check your budget weekly or biweekly to stay accountable and make real-time adjustments.

Finally, don’t be too hard on yourself if you don’t see results immediately. Building a budget that works takes time and patience. Focus on progress, not perfection, and keep refining your approach. Over time, you’ll gain a clearer understanding of your financial habits and how to manage them effectively. With consistency and dedication, your budget will become a powerful tool for achieving your financial dreams. Start today, and take control of your money for a brighter tomorrow.

The Ultimate Guide to Creating a Personal Budget

**The Ultimate Guide to Creating a Personal Budget**

Managing your finances can feel overwhelming, but creating a personal budget is one of the most effective ways to take control of your money. A budget helps you track income, expenses, and savings, ensuring you live within your means and work toward your financial goals. Whether you’re saving for a vacation, paying off debt, or planning for retirement, a budget is your roadmap to financial stability. The key to a successful budget is simplicity and consistency. You don’t need complex spreadsheets or financial expertise—just a clear plan and the discipline to stick to it. Start by understanding your current financial situation, including your monthly income and expenses. This foundation will help you build a budget that works for your lifestyle.

The first step in creating a budget is to identify your income sources. This includes your salary, freelance earnings, investments, or any other money you receive regularly. Be sure to use your *net income* (the amount after taxes and deductions) for an accurate picture. Once you know how much you earn, list all your monthly expenses. These fall into two categories: fixed expenses (rent, utilities, insurance) and variable expenses (groceries, entertainment, dining out). Tracking your spending for a month can help you identify where your money goes. Many budgeting apps and tools can simplify this process, but a notebook or spreadsheet works just as well.

With your income and expenses in hand, the next step is to allocate your money wisely. A popular budgeting method is the **50/30/20 rule**: 50% of your income goes to needs (essentials like rent and groceries), 30% to wants (entertainment, hobbies), and 20% to savings and debt repayment. However, this rule isn’t one-size-fits-all. Adjust the percentages based on your priorities. For example, if you’re paying off high-interest debt, you might allocate more to that category. The goal is to ensure your expenses don’t exceed your income and that you’re saving for the future.

One of the biggest budgeting challenges is managing variable expenses, which can easily spiral out of control. To tackle this, set spending limits for categories like dining out, shopping, and entertainment. Use cash or prepaid cards to stick to these limits, as it’s harder to overspend when you’re physically handing over money. Additionally, plan for irregular expenses like car repairs or holiday gifts by setting aside a small amount each month. This prevents these costs from derailing your budget when they arise.

Saving money is a critical part of any budget, but it’s often the first thing people sacrifice when expenses rise. To make saving a priority, treat it like a fixed expense. Set up automatic transfers from your checking account to a savings or investment account. Even small contributions add up over time. If you’re struggling to save, look for ways to cut unnecessary expenses, such as subscription services you rarely use or daily coffee runs. Every dollar saved brings you closer to your financial goals.

Debt can feel like a heavy burden, but a budget can help you tackle it systematically. Start by listing all your debts, including credit cards, student loans, and personal loans, along with their interest rates and minimum payments. Focus on paying off high-interest debt first while continuing to make minimum payments on the others. Consider the *debt snowball method* (paying off the smallest debts first) or the *debt avalanche method* (targeting high-interest debts first) to stay motivated. Incorporate debt repayment into your budget to ensure consistent progress.

Life is unpredictable, and your budget should be flexible enough to adapt to changes. Review your budget monthly to ensure it aligns with your goals and circumstances. If your income increases, allocate the extra money to savings or debt repayment. If expenses rise, look for areas to cut back. Regularly updating your budget keeps you on track and helps you make informed financial decisions. Remember, budgeting isn’t about restriction—it’s about making intentional choices with your money.

Creating and maintaining a personal budget requires effort, but the rewards are well worth it. You’ll gain clarity over your finances, reduce stress, and move closer to achieving your goals. Start small, be patient with yourself, and celebrate your progress along the way. With time, budgeting will become second nature, and you’ll wonder how you ever managed without it. Take the first step today—your future self will thank you.

The Benefits of Tracking Your Spending

**The Benefits of Tracking Your Spending**

Understanding where your money goes each month is more than just a financial habit—it’s a powerful tool for gaining control over your life. Tracking your spending allows you to see exactly how much you’re allocating to essentials like rent, groceries, and utilities, as well as discretionary expenses like dining out or entertainment. This clarity helps you identify patterns and make informed decisions about your finances. By recording every purchase, no matter how small, you create a detailed snapshot of your financial behavior. This awareness is the first step toward breaking bad spending habits and building healthier ones. Whether you use a notebook, a spreadsheet, or a budgeting app, the act of tracking fosters mindfulness about your money, ensuring that every dollar is spent intentionally.

One of the most immediate benefits of tracking your spending is the ability to spot unnecessary expenses. Small, recurring costs—like daily coffee runs or subscription services you rarely use—can add up quickly without you even noticing. When you log your purchases, these patterns become obvious. For example, you might realize that you’re spending $50 a month on streaming services you barely watch. By identifying these leaks, you can cut back and redirect that money toward savings, debt repayment, or other financial goals. This process not only frees up cash but also empowers you to prioritize what truly matters to you.

Tracking your spending is essential for creating a realistic budget that works for your lifestyle. Without a clear understanding of your expenses, budgeting becomes a guessing game. By analyzing your spending habits, you can allocate funds more effectively, ensuring that you’re covering your needs while still allowing room for the things you enjoy. A well-informed budget helps you avoid overspending and reduces financial stress. It also provides a roadmap for achieving long-term goals, whether that’s buying a home, traveling, or retiring comfortably. When you know exactly where your money is going, you can adjust your spending to align with your priorities.

Financial stress often stems from uncertainty about where your money is going. Tracking your spending eliminates this uncertainty, giving you a sense of control and confidence in your financial decisions. When you know you’re sticking to a plan, you’re less likely to feel anxious about unexpected expenses or worry about running out of money before the end of the month. This peace of mind can improve your overall well-being, reducing the mental burden that comes with financial uncertainty. It also encourages a proactive approach to money management, rather than a reactive one.

Tracking your spending is a cornerstone of saving money and achieving financial goals. When you have a clear picture of your expenses, it’s easier to set aside funds for emergencies, vacations, or major purchases. For instance, if you’re saving for a down payment on a house, tracking your spending helps you identify areas where you can cut back to accelerate your savings. It also keeps you accountable, as you can regularly review your progress and make adjustments as needed. Over time, this disciplined approach can lead to significant financial milestones.

Debt can feel overwhelming, but tracking your spending is a practical way to tackle it head-on. By understanding your cash flow, you can allocate more money toward paying off high-interest debts like credit cards or loans. Additionally, tracking helps you avoid behaviors that contribute to debt, such as overspending or relying on credit for non-essential purchases. As you reduce your debt, you’ll also improve your credit score, opening up opportunities for better interest rates and financial flexibility in the future. It’s a win-win situation that starts with the simple act of monitoring your expenses.

Tracking your spending isn’t just about restriction—it’s also about making room for the things that bring you joy. When you have a clear budget, you can allocate funds for hobbies, travel, or treats without feeling guilty. This balance ensures that your financial plan is sustainable and enjoyable, rather than a source of deprivation. By prioritizing what truly matters to you, you create a healthier relationship with money, one that supports both your present happiness and your future security.

Finally, tracking your spending is a habit that pays dividends over time. It teaches you valuable skills like discipline, planning, and self-awareness, which are essential for long-term financial success. As you become more attuned to your spending habits, you’ll naturally make smarter financial decisions, whether you’re negotiating a raise, investing in the stock market, or planning for retirement. It’s an investment in yourself that yields benefits far beyond your monthly budget. Start tracking today, and take the first step toward a more secure and fulfilling financial future.

Frugal Living: How to Save Money Without Sacrificing Fun

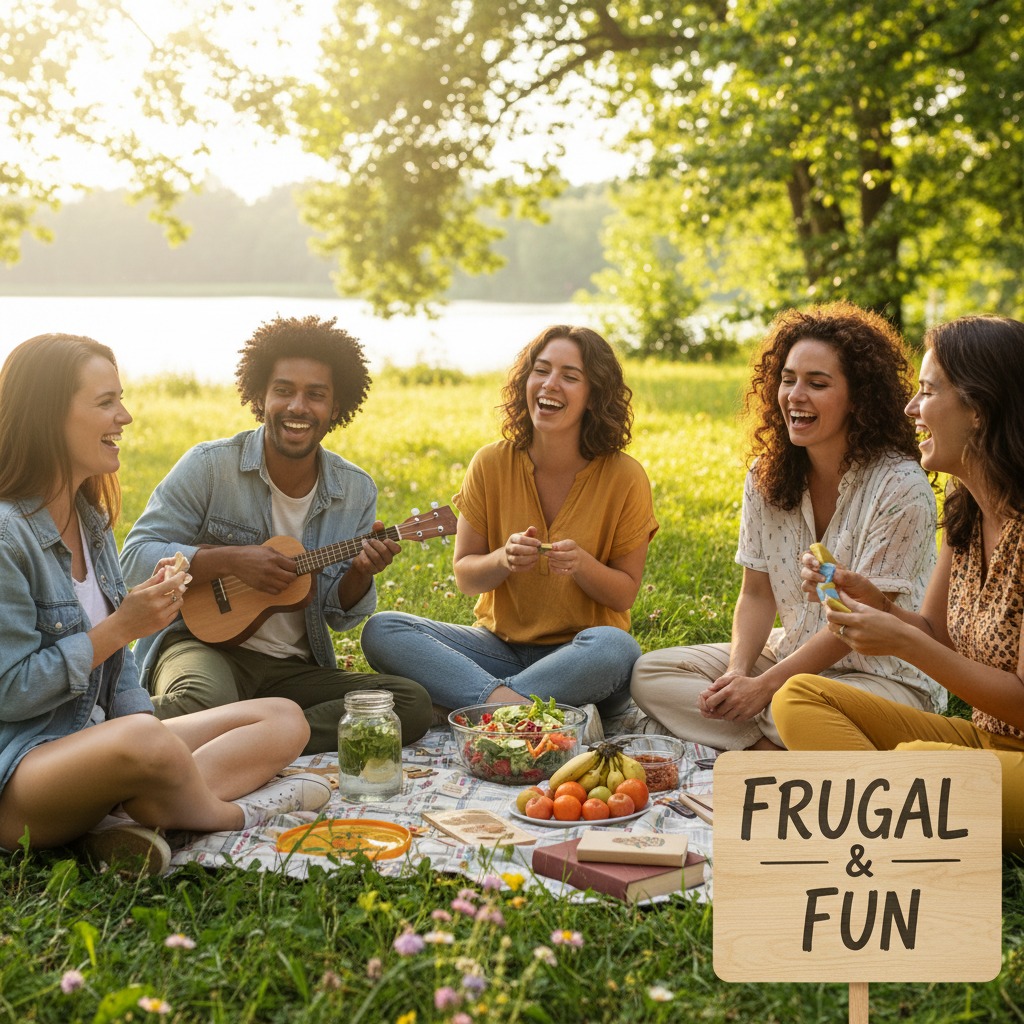
A diverse group of five friends laughs and eats together on a picnic blanket by a lake while one plays the ukulele.

Living frugally doesn’t mean giving up the joys of life. It’s about making smart choices that allow you to save money while still enjoying the things you love. By redefining what “fun” means and finding creative ways to cut costs, you can achieve financial stability without feeling deprived. The key is to prioritize what truly matters to you and let go of unnecessary expenses. This approach not only helps your wallet but also fosters a more intentional and fulfilling lifestyle.

One of the simplest ways to embrace frugal living is by creating a budget. Start by tracking your monthly expenses to identify areas where you can cut back. Allocate a portion of your income to savings, essentials, and leisure. A budget doesn’t restrict you; it empowers you to spend mindfully. Tools like budgeting apps or spreadsheets can make this process easier and more efficient.

Cooking at home is another effective way to save money while still enjoying delicious meals. Eating out or ordering takeout frequently can drain your finances. Instead, plan meals for the week, shop with a grocery list, and experiment with affordable, tasty recipes. Hosting potluck dinners with friends can also be a fun and cost-effective way to socialize.

Entertainment doesn’t have to be expensive. Look for free or low-cost activities in your community, such as local festivals, park picnics, or museum days. Streaming services offer affordable access to movies and shows, and many libraries lend DVDs for free. Get creative with at-home entertainment, like game nights or DIY projects, to keep the fun alive without overspending.

Traveling on a budget is entirely possible with a bit of planning. Opt for off-peak seasons, use travel rewards, and consider alternative accommodations like hostels or Airbnb. Road trips can be more affordable than flying, and exploring local destinations can be just as rewarding as international travel. The goal is to experience new places without breaking the bank.

Shopping secondhand is a frugal and sustainable way to update your wardrobe or home decor. Thrift stores, consignment shops, and online platforms like eBay or Poshmark offer quality items at a fraction of the cost. You can also organize clothing swaps with friends to refresh your closet without spending a dime.

Cutting subscription services you rarely use can free up a surprising amount of money. Review your monthly subscriptions and cancel those that don’t add value to your life. Many services, like gym memberships or streaming platforms, can be shared with family or friends to split the cost.

Learning to DIY can save you money on everything from home repairs to gifts. YouTube tutorials and online courses make it easy to acquire new skills, whether it’s fixing a leaky faucet or crafting personalized presents. Not only does this save money, but it also provides a sense of accomplishment.

Frugal living extends to social gatherings too. Instead of meeting at expensive restaurants or bars, suggest budget-friendly alternatives like coffee dates, potluck dinners, or outdoor activities. Your friends will likely appreciate the opportunity to save money while still enjoying each other’s company.

Reducing energy consumption at home is both frugal and environmentally friendly. Simple changes like using energy-efficient light bulbs, unplugging devices when not in use, and adjusting your thermostat can lead to significant savings on utility bills. Investing in a programmable thermostat or smart home devices can also help optimize energy usage.

Building an emergency fund is a cornerstone of frugal living. Aim to save at least three to six months’ worth of living expenses in case of unexpected events like job loss or medical emergencies. Even small contributions to your emergency fund each month can provide peace of mind and financial security.

Frugal living isn’t about deprivation; it’s about finding joy in simplicity. Focus on experiences and relationships rather than material possessions. A walk in nature, a good book from the library, or a heartfelt conversation with a loved one can be just as fulfilling as expensive outings or purchases.

Staying motivated on your frugal living journey is essential. Celebrate small victories, like paying off a debt or reaching a savings goal, to keep yourself inspired. Surround yourself with like-minded individuals who share your values and can offer support and encouragement.

Ultimately, frugal living is about aligning your spending with your values and long-term goals. By making conscious choices and finding creative ways to save, you can enjoy a rich and fulfilling life without overspending. It’s not about living less; it’s about living smarter.