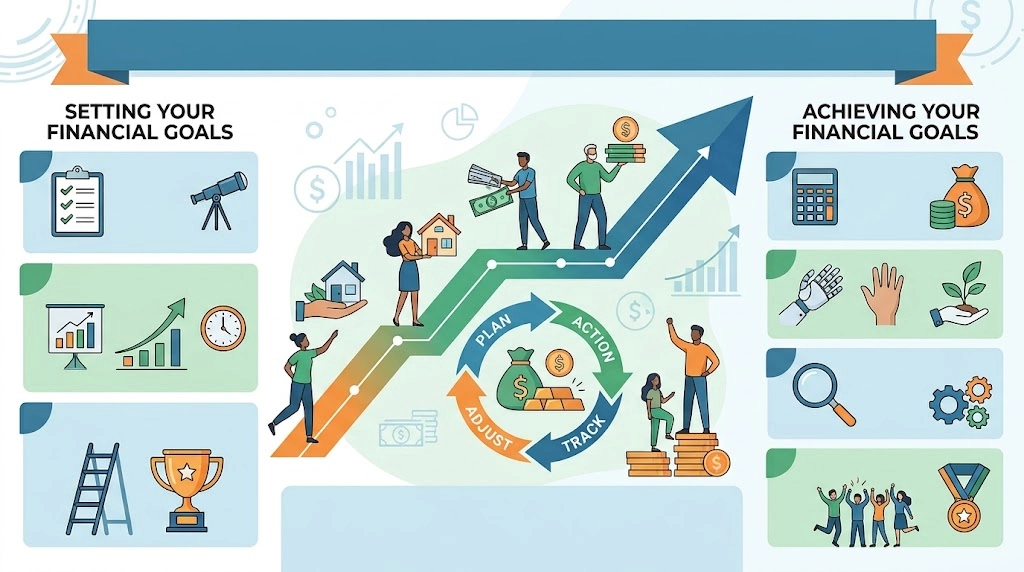
Financial goals are the cornerstone of a secure and fulfilling life. Whether it’s saving for a dream home, paying off debt, or building an emergency fund, having clear objectives gives direction to your financial decisions. However, setting goals is just the first step; achieving them requires discipline, planning, and consistency. Start by identifying what truly matters to you. Are you saving for short-term needs like a vacation, or long-term goals like retirement? Prioritize based on urgency and importance. Break larger goals into smaller, manageable milestones to avoid feeling overwhelmed. For instance, instead of focusing solely on “saving $50,000,” aim to save $500 per month. This approach makes progress measurable and motivates you to stay on track.
Once you’ve defined your goals, assess your current financial situation. Understanding your income, expenses, and debt is crucial. Create a budget to track where your money goes each month. Tools like budgeting apps or spreadsheets can simplify this process. Identify areas where you can cut unnecessary spending and redirect those funds toward your goals. For example, reducing daily coffee shop visits or canceling unused subscriptions can free up significant amounts over time. Be honest with yourself about your spending habits—small changes often lead to big results.
Saving money is essential for achieving financial goals, but it’s equally important to make your savings work harder. Explore high-yield savings accounts, certificates of deposit (CDs), or investment options like stocks and mutual funds, depending on your risk tolerance and time horizon. For long-term goals, such as retirement, consider tax-advantaged accounts like a 401(k) or IRA. Diversifying your savings ensures you’re maximizing returns while minimizing risk. Consult a financial advisor if you’re unsure where to start.
Debt can be a major obstacle to achieving financial goals. Develop a strategy to tackle it systematically. The debt snowball method, which focuses on paying off the smallest debts first, can provide quick wins and motivation. Alternatively, the debt avalanche method prioritizes high-interest debts to save money in the long run. Whichever approach you choose, commit to making consistent payments and avoid taking on new debt. Celebrate each milestone, like paying off a credit card, to stay motivated.
Life is unpredictable, and financial goals need to be flexible. Regularly review and adjust your plans as circumstances change. Did you get a raise? Increase your savings contributions. Facing unexpected expenses? Temporarily pause non-essential savings goals without losing sight of the bigger picture. Building an emergency fund with three to six months’ worth of living expenses can provide a safety net during tough times. Flexibility ensures your goals remain achievable, no matter what life throws your way.
Accountability is a powerful tool for staying on track. Share your financial goals with a trusted friend or family member who can offer support and encouragement. Consider joining a financial accountability group or working with a financial coach. Tracking your progress visually, such as with a chart or app, can also keep you motivated. Celebrate small victories along the way—they’re proof that you’re moving closer to your ultimate goal.
Financial literacy is key to making informed decisions. Educate yourself about personal finance through books, podcasts, and online courses. Understand concepts like compound interest, inflation, and diversification. The more you know, the better equipped you’ll be to navigate financial challenges and opportunities. Start with the basics and gradually expand your knowledge. Remember, learning is an ongoing process, and every bit of knowledge brings you closer to financial success.
Avoid common pitfalls that can derail your financial goals. Impulse buying, lifestyle inflation, and lack of planning are frequent obstacles. Before making a purchase, ask yourself if it aligns with your priorities. Resist the urge to increase spending just because your income rises. Stick to your budget and regularly reassess your goals to ensure they remain realistic and relevant. Being mindful of these traps will help you stay focused and disciplined.
Achieving financial goals is a marathon, not a sprint. Be patient and trust the process. Progress may seem slow at times, but consistency pays off in the long run. Remind yourself of the reasons behind your goals—whether it’s financial independence, a secure retirement, or a better life for your family. Stay positive and keep pushing forward, even when faced with setbacks. Your future self will thank you for the effort you’re putting in today.
Finally, take time to celebrate your achievements. Reaching a financial goal, no matter how small, is a significant accomplishment. Treat yourself to something meaningful, but avoid overspending. Reflect on how far you’ve come and use that momentum to set new goals. Financial success is not just about the destination—it’s about the habits and mindset you develop along the way. With determination and a clear plan, you can turn your financial dreams into reality.